Calculate Your EPS Pension
EPS Pension Calculator India 2026 — EPFO Formula, Real Examples & FAQs | Wealthpedia
Your estimated EPS pension
The calculator estimates your monthly pension using your:
- Pensionable salary
- Pensionable service
- Applicable service weightage
- Pension commencement age
- Early or deferred pension provisions, where applicable
Important: This calculator provides an estimate for planning purposes. Your actual pension is determined by EPFO based on your service records, pensionable salary and the provisions applicable to your membership.
How Is EPS Pension Calculated?
For eligible members, the basic EPS pension formula is:
Monthly EPS Pension = Pensionable Salary × Pensionable Service ÷ 70
The formula is specified under the Employees’ Pension Scheme, 1995. (EPF India)
Example
Suppose:
- Pensionable salary = ₹15,000
- Pensionable service = 20 years
- Applicable two-year weightage = 2 years
Effective pensionable service = 22 years
Therefore:
₹15,000 × 22 ÷ 70 = ₹4,714 per month
This is an illustration. Your actual pension may differ depending on your service history, pensionable salary and applicable EPS provisions.
What Is EPS Pension?
The Employees’ Pension Scheme, 1995, or EPS-95, is administered by the Employees’ Provident Fund Organisation (EPFO).
EPS provides monthly pension benefits for eligible members and certain family members. EPFO identifies EPS as one of the three major social-security schemes administered under the EPF framework. (EPF India)
Unlike EPF, EPS is a defined-benefit pension scheme. You should therefore not think of EPS as an individual investment account containing a personal pension balance.
The pension amount is determined using the applicable EPS rules, including pensionable salary and pensionable service.
What Is EPS and Who Is Covered?
The Employees’ Pension Scheme (EPS-95) is administered by the Employees’ Provident Fund Organisation (EPFO) and was introduced on November 16, 1995. It provides a monthly pension to members of the organised sector workforce upon retirement, and to their family members upon death.
Who contributes to EPS?
Your employer contributes 12% of your Basic + Dearness Allowance (DA) to the EPF ecosystem. Of this 12%, 8.33% goes into EPS and only 3.67% goes into your EPF account. You, as the employee, contribute nothing directly to EPS — your full 12% goes to EPF.
Who is eligible?
- All employees earning a Basic + DA of ₹25,000 or less per month are mandatory EPS members.
- Employees earning above ₹25,000 can also be EPS members (contributions may be capped unless they opted for Higher Pension).
- Minimum 10 years of contributory service is required to receive a monthly pension.
- Members with fewer than 10 years of service can withdraw their EPS accumulation as a lump sum (Scheme Certificate or withdrawal).
When does pension begin?
Normal pension begins at age 58. Members with 10+ years of service can opt for early pension from age 50 (at a reduced rate) or defer pension up to age 60 (at an enhanced rate).
Component 1: Pensionable Salary
This is the average of your last 60 months of Basic + DA, capped at ₹25,000 per month — unless you are a Higher Pension member (see below).
The salary cap means that even if you earn ₹80,000 a month, your pensionable salary is still ₹25,000 for the pension calculation. This is why the maximum monthly pension under standard EPS is ₹7,500 (₹15,000 × 35 ÷ 70).
Higher Pension Exception: Following the Supreme Court order in November 2022, employees who were EPFO members before September 1, 2014, and whose employers paid EPS contributions on the actual salary (not capped), had a window to jointly apply for Higher Pension. If you are a Higher Pension member, your actual average salary — not capped at ₹15,000 — is used in the formula.
Component 2: Pensionable Service
This is your total years of EPS contributions, with three important rules:
Rule A — Rounding: If you have 6 or more months in a partial year, it rounds up to a full year. If you have fewer than 6 months, those months are dropped. So 24 years and 8 months becomes 25 years; 24 years and 4 months stays at 24 years.
Rule B — Maximum: Pensionable service is capped at 35 years.
Rule C — 20-Year Bonus: If your rounded pensionable service is 20 years or more, EPFO adds a 2-year bonus to your service count. So someone with 25 years of service gets an effective service of 27 years. This is a significant boost that most calculators miss entirely.
Component 3: The Divisor (70)
This is fixed. It is part of the EPS-95 formula and does not change.
Age Adjustments
Early Pension (age 50–57): If you choose to start your pension before age 58, the pension is reduced by 4% for each year before 58. Starting at 55 means a 12% reduction; at 50, a 32% reduction. You must have completed 10 years of service, and you must not be in active employment.
Deferred Pension (age 59–60): If you delay starting your pension after 58 (up to maximum age 60), the pension is increased by 4% per year. Waiting until 60 gives you an 8% enhancement.
Minimum Pension Floor: Regardless of the formula output, EPFO guarantees a minimum of ₹1,000 per month for eligible members (those with 10+ years of service). Note that the Parliamentary Standing Committee has formally recommended increasing this floor — watch for updates.
EPS Pension Calculator 2026: What Changed?
A major EPFO change took effect in September 2026.
The statutory wage ceiling for mandatory EPFO coverage increased from:
₹15,000 → ₹25,000 per month
effective 17 September 2026. The Government said the change would bring employees earning between ₹15,000 and ₹25,000 within mandatory EPFO coverage, subject to the applicable scheme provisions. (Press Information Bureau)
Important: ₹25,000 EPFO ceiling does not automatically mean ₹25,000 EPS pensionable salary
These are two different concepts.
Concept
Amount
Earlier EPFO mandatory-coverage wage ceiling
₹15,000
EPFO mandatory-coverage wage ceiling from 17 Sept 2026
₹25,000
Standard EPS pensionable-salary ceiling under the EPS-95 provision
₹15,000
Higher-pension cases
Subject to applicable provisions
The September 2026 change therefore should not be interpreted as meaning that every existing EPS member’s pension is automatically recalculated using ₹25,000 as pensionable salary. The standard EPS-95 provision continues to specify ₹15,000 as the maximum pensionable salary, while separate provisions apply to eligible higher-wage pension cases. (EPF India)
Does the ₹25,000 Wage Ceiling Increase My EPS Pension?
Not automatically.
The 2026 increase primarily raises the wage ceiling used for determining mandatory EPFO coverage.
Your EPS pension depends on factors such as:
- Your eligible EPS membership
- Pensionable salary
- Pensionable service
- Applicable service weightage
- Pension commencement age
- Whether higher-pension provisions apply to you
Therefore, an employee earning ₹25,000 does not automatically receive an EPS pension calculated as:
₹25,000 × service ÷ 70
unless the applicable EPS provisions permit that pensionable salary to be used for that member.
EPS Withdrawal Benefit: What Happens If You Leave Before 10 Years
If you leave employment before completing 10 years of EPS contributory service, you are not entitled to a monthly pension. Instead, EPFO provides a one-time EPS Withdrawal Benefit — a lump sum calculated using official Table-D factors based on your completed years of service and pensionable salary.
This section covers exactly how the withdrawal benefit is calculated, what Table-D says, when to take it versus preserving service via a Scheme Certificate, the tax treatment, and the exact claim process. These are the most-searched questions on EPS that are not answered elsewhere on this page — because they apply to a different situation than monthly pension.
What Is the EPS Withdrawal Benefit?
The EPS Withdrawal Benefit is a lump-sum payment EPFO makes when a member exits the scheme with fewer than 10 years of qualifying service. It compensates the member for the employer’s EPS contributions made on their behalf, using a standardised factor table rather than the actual contributions or the full EPF corpus.
It is important to be clear about what it is not: it is not a refund of the actual contributions. The employer contributes 8.33% of pensionable salary to EPS every month, but the withdrawal benefit you receive is determined by Table-D — which may be more or less than the actual cumulative contributions depending on years of service and assumed returns.
EPS Table-D: The Official Withdrawal Benefit Factors
EPFO’s Table-D specifies a multiplier for each completed year of service. The withdrawal benefit equals the pensionable salary multiplied by the Table-D factor for the relevant year. Pensionable salary is capped at ₹25,000 per month for standard EPS members (or the actual salary for Higher Pension members).
Important rounding rule for withdrawal benefit: Unlike the pension formula (where 6+ months rounds up), withdrawal benefit uses only completed full years. Partial years are not counted — so 3 years and 11 months gives the same benefit as exactly 3 years.
| Completed Years of EPS Service | Table‑D Factor | Withdrawal Benefit (₹15,000 salary) | Withdrawal Benefit (₹10,000 salary) |
|---|---|---|---|
| 1 year | 1.02 | ₹15,300 | ₹10,200 |
| 2 years | 1.99 | ₹29,850 | ₹19,900 |
| 3 years | 2.98 | ₹44,700 | ₹29,800 |
| 4 years | 3.99 | ₹59,850 | ₹39,900 |
| 5 years | 5.02 | ₹75,300 | ₹50,200 |
| 6 years | 6.07 | ₹91,050 | ₹60,700 |
| 7 years | 7.13 | ₹1,06,950 | ₹71,300 |
| 8 years | 8.22 | ₹1,23,300 | ₹82,200 |
| 9 years | 9.33 | ₹1,39,950 | ₹93,300 |
Notes:
- Table‑D factors are as per EPS-95 scheme rules.
- Withdrawal Benefit = Pensionable Salary × Table‑D Factor
- Minimum 1 completed year of EPS service is required
Example — Withdrawal Benefit Calculation: Rahul worked for 7 years and 9 months. His pensionable salary was ₹15,000. His completed years = 7 (9 months is partial, not counted). Table-D factor for 7 years = 7.13. Withdrawal benefit = ₹15,000 × 7.13 = ₹1,06,950.
The Wealthpedia EPS Pension Calculator now includes a built-in EPS Withdrawal Benefit tab that automatically activates when your service is below 10 years. It shows your estimated amount, the Table-D factor applied, and a full reference table — so you never need to look up Table-D manually again.
Scheme Certificate vs EPS Withdrawal: Which Should You Choose?
This is the most consequential decision a short-tenure EPS member faces — and the default instinct to “take the money now” is often wrong. Here is a structured framework.
| Factor | Take EPS Withdrawal Benefit | Get Scheme Certificate |
|---|---|---|
| Future employment | You will never work in an EPF‑covered organisation again | You may or will return to organised sector employment |
| Service close to 10 years | Only 1–3 years, unlikely to bridge the gap | 7–9 years — one more EPF-covered job pushes you past the threshold |
| Amount received now | Table‑D lump sum credited immediately | Nothing now — service is preserved |
| Future benefit | No pension eligibility from this service | Prior service gets added; total may reach 10 years eligibility |
| Tax on receipt | Taxable if received before 5 years of continuous service | No tax event — no withdrawal, only preservation |
| Reversibility | Irreversible — once withdrawn, service is erased | Reversible — certificate can be used later for pension claim |
Decision framework: Scheme Certificate vs EPS Withdrawal. For anyone with 7–9 years of service considering organised sector employment, the Scheme Certificate is almost always the better choice.
The key rule of thumb: If you have 7 or more years of EPS service and any realistic chance of returning to organised sector employment, choose the Scheme Certificate. The monthly pension you would eventually receive over a 20-year retirement will almost always exceed the lump-sum withdrawal benefit — often by a multiple of 3 to 5 times.
Consider: 9 years of service, ₹25,000 salary → withdrawal benefit of ₹1,39,950. But if that 9-year service is preserved and later combined with just 1 more year (reaching 10 years), the member becomes eligible for a monthly pension of approximately ₹(25,000 × 10 ÷ 70) = ₹2,143/month, or roughly ₹25,716/year — meaning the preserved service pays back the forgone ₹1.4 lakh in just 5.4 years, and then continues for life.
Is EPS Withdrawal Benefit Taxable?
Yes, but with an important nuance tied to service length and continuity.
Tax-free scenario: If you have completed 5 or more years of continuous service (across employers, with unbroken EPF contribution and UAN transfer — not withdrawal), the EPS withdrawal benefit is exempt from tax under Section 10(12) of the Income Tax Act, similar to EPF withdrawal rules.
Taxable scenario: If total continuous service is less than 5 years — meaning you withdrew EPF at some point and broke the continuity — the EPS withdrawal benefit is taxable in the year of receipt, added to your other income, and taxed at your applicable slab rate. TDS at 10% is deducted by EPFO if the amount exceeds ₹50,000 and you do not submit Form 15G/15H (for those eligible).
Practical implication: If you have 4 years and 10 months of unbroken service and are considering withdrawing, waiting just 2 more months to cross the 5-year mark could make the entire withdrawal tax-free. The difference at a 20% or 30% tax bracket on ₹70,000–₹1,20,000 of withdrawal benefit can be ₹14,000–₹36,000 — meaningful enough to plan around.
Always consult a tax advisor for your specific situation, especially if your service spans multiple employers or involves breaks in EPF contribution.
How to Verify Your EPS Service and Contributions Before You Calculate
The single most common error people make with EPS calculations — both on this calculator and in their own planning — is using the wrong service figure. Here is exactly how to get the correct number from EPFO records.
Step 1: Check Your EPFO Passbook
Log into the EPFO member portal at unifiedportal-mem.epfindia.gov.in using your UAN. Go to View → Passbook. You will see a separate passbook for each PF account (each employer) linked to your UAN.
The passbook shows monthly entries with the month and year of contribution. Count the total months across all accounts where EPS contributions appear — this is your total EPS service. Divide by 12 for years and keep the remainder as months to enter into the calculator.
Step 2: Confirm EPS Contributions Are Correctly Split
Each monthly passbook entry should show a split: a portion to EPF (employee contribution + 3.67% employer) and a portion to EPS (8.33% employer). If your passbook shows only EPF contributions and no EPS line, it could indicate:
- Your employer was exempted from EPS (rare, for certain trusts)
- Your salary exceeded the EPS threshold and you were excluded at some point
- A data entry error — raise a grievance with EPFO if EPS entries are missing despite being an EPF member
Step 3: Check for Gaps in Service
If you changed jobs and withdrew your EPF/EPS between employers rather than transferring, those years of service are lost from your EPS record. A withdrawal using Form 19 (EPF) and Form 10-C (EPS) resets the clock. This is the most common reason people discover their actual EPS service is shorter than their total career length.
The Wealthpedia Financial Health Score tool includes an EPF health check module that helps you identify contribution gaps and evaluate your overall retirement readiness — use it alongside this calculator for a complete picture.
How to Use the Wealthpedia EPS Pension Calculator: A Step-by-Step Guide
The calculator has two sections: an input form on the left, and a four-tab results panel on the right. Here is exactly what to enter and how to read the output.
Step 1: Enter Your Average Basic + DA (Last 60 Months)
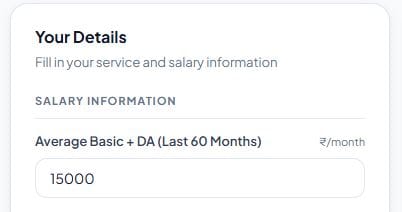
This is your average monthly Basic Salary plus Dearness Allowance over the last five years. If you are mid-career, use your current Basic + DA as a reasonable proxy.
Do not include HRA, LTA, bonuses, or any other components — only Basic and DA count.
If you are salaried in the private sector and your salary slip shows no DA separately, your Basic alone is the figure to use.
Where to find this number: Your salary slip, EPFO passbook, or Form 16. For the most accurate figure, average your last 60 months’ Basic + DA from your payslips.
Step 2: Choose Higher Pension or Standard Cap
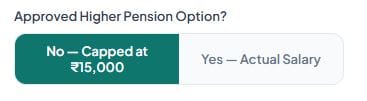
If you are a standard EPS member, leave this on “No — Capped at ₹15,000”. Your pensionable salary will be capped regardless of what you enter.
If you jointly applied with your employer for Higher Pension under the Supreme Court 2022 ruling and your application was approved, select “Yes”. The calculator will use your actual salary figure.
Step 3: Enter Your Service Years and Additional Months
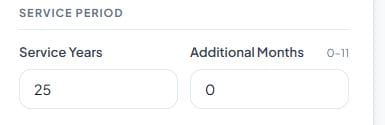
Enter your total EPS contributory service across all employers. This is not your current employer’s service — it is your total career service where EPS contributions were made.
When you switch jobs, the EPS credit transfers via your UAN.
Enter the additional months separately (0–11). The calculator applies the official rounding rule automatically.
Pro tip: Check your EPFO passbook on the member portal (unifiedportal-mem.epfindia.gov.in) to confirm your actual service period. Many people undercount service from early-career jobs.
Step 4: Select Your Pension Start Age
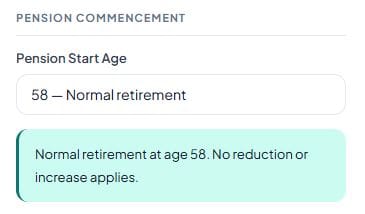
Use the dropdown to choose your planned pension start age. The options are 50 through 60, with the age adjustment automatically calculated and displayed. The info box beneath the dropdown updates in real time to show the exact percentage impact.
For most people planning ahead, running the calculator at 58, 59, and 60 to compare outcomes is useful — which is exactly what the Age Scenarios tab does automatically.
Step 5: Enter Your Expected Life Span
This is used only to calculate the Lifetime Total figure — the total pension receipts over your expected retirement years. The EPFO actuarial assumption for Indian EPS is around 75–78 years for urban workers, but personal health history may warrant a higher number. The default of 80 is reasonable for planning purposes.
Step 6: Click “Calculate My EPS Pension →”
Results populate across four tabs.
Reading the Results: Tab by Tab
Summary Tab: The large teal card shows your monthly pension. Below it, the Annual Pension, Replacement Ratio (pension as % of current salary), and Lifetime Total are shown. A status pill at the top tells you whether your pension represents strong (≥40%), moderate (20–39%), or low (<20%) income replacement. The formula is shown with your actual numbers substituted in, so you can verify the arithmetic.
Calculation Steps Tab: Every step in the calculation is shown in sequence with labels. A “CAPPED” tag shows if your salary was limited to ₹15,000. A “+2 YRS” tag shows if the 20-year bonus applied. “ROUNDED UP” confirms month rounding. “FLOOR APPLIED” alerts you if the minimum ₹1,000 floor was triggered. This tab is your audit trail.
Age Scenarios Tab: All eleven ages from 50 to 60 are shown in a comparison table (desktop) or stacked cards (mobile), with monthly pension, adjustment percentage, annual pension, and lifetime total for each. Your selected age is highlighted. This lets you make an informed decision about whether to take early pension, wait for 58, or defer to 59–60.
Family Pension Tab: Shows estimated widow pension (approximately 50% of member pension, per EPFO Table-C), child pension (25% of widow pension per child, up to two children), and orphan pension (75% of widow pension per child). All figures respect the ₹1,000 minimum. These are approximations — actual amounts follow EPFO Table-C — but they are useful for retirement planning conversations with your family.
EPS Pension Calculation Examples
Example 1: Factory Worker — Ramesh, 30 Years of Service, Standard EPS
Profile: Ramesh works at a manufacturing company. His Basic + DA has averaged ₹15,000 over the last five years (the cap applies regardless). He has 30 years and 7 months of service. He plans to retire at 58.
Inputs:
- Average Salary: ₹25,000
- Higher Pension: No
- Service: 30 years, 7 months
- Pension Start Age: 58
Calculation:
- Pensionable Salary: ₹15,000 (at cap)
- Rounding: 7 months ≥ 6, so rounds up to 31 years
- 20-Year Bonus: Applicable (31 ≥ 20), so +2 years
- Effective Service: 33 years
- Base Pension: (15,000 × 33) ÷ 70 = ₹7,071/month
- Age Adjustment: None (retiring at 58)
- Final Pension: ₹7,071/month
Annual Pension: ₹84,857
Lifetime Total (to age 80): ₹18.67 lakh
This is close to the maximum possible under standard EPS. Ramesh’s EPS pension alone covers basic monthly expenses in a smaller city. When combined with his EPF corpus and other savings, his retirement planning picture is solid for a lean lifestyle.
Example 2: IT Professional — Priya, High Salary, Standard Cap
Profile: Priya is a software engineer. Her Basic + DA has averaged ₹65,000 per month. She has 18 years and 4 months of service. She plans to retire at 58.
Inputs:
- Average Salary: ₹65,000
- Higher Pension: No
- Service: 18 years, 4 months
- Pension Start Age: 58
Calculation:
- Pensionable Salary: ₹15,000 (salary capped — ₹65,000 not used)
- Rounding: 4 months < 6, so stays at 18 years
- 20-Year Bonus: Not applicable (18 < 20)
- Effective Service: 18 years
- Base Pension: (15,000 × 18) ÷ 70 = ₹3,857/month
- Final Pension: ₹3,857/month
Replacement Ratio: 3,857 ÷ 65,000 = 5.9% — very low
The insight here is critical. Priya earns ₹65,000 in Basic alone, but her EPS pension is only ₹3,857. Her salary is irrelevant above the cap. For someone like Priya, EPS is a minor income floor — the real retirement work must be done by her SIP corpus, NPS, and EPF. This is why high-income earners need a separate retirement corpus calculator rather than relying on EPS estimates.
If Priya had opted for Higher Pension (actual salary used):
- Pensionable Salary: ₹65,000
- Base Pension: (65,000 × 18) ÷ 70 = ₹16,714/month
- Replacement Ratio: 25.7% — meaningfully better
But this comes at a cost: employer contributions that previously flowed to EPF now flow to EPS, reducing her EPF corpus. The trade-off depends on longevity and investment preferences.
Example 3: Early Pension — Suresh, Retiring at 55
Profile: Suresh has 22 years and 8 months of service. His Basic + DA is ₹15,000. He wants to retire at 55 due to health reasons.
Inputs:
- Average Salary: ₹15,000
- Service: 22 years, 8 months
- Pension Start Age: 55
Calculation:
- Pensionable Salary: ₹15,000
- Rounding: 8 months ≥ 6, rounds up to 23 years
- 20-Year Bonus: Applicable (+2 years)
- Effective Service: 25 years
- Base Pension: (15,000 × 25) ÷ 70 = ₹5,357/month
- Early Pension Reduction: (58 − 55) × 4% = 12% reduction
- Reduction Amount: ₹643
- Final Pension: ₹4,714/month
By retiring 3 years early, Suresh sacrifices ₹643/month permanently. Over a 25-year retirement (to age 80), this means he receives roughly ₹1.93 lakh less in lifetime pension. However, he also starts receiving pension 3 years earlier, collecting ₹4,714 × 36 = ₹1.70 lakh during those early years. The net early-pension trade-off here is roughly neutral around age 83 — making the decision personal rather than mathematical.
The Age Scenarios tab in the calculator shows this comparison instantly for all ages from 50 to 60.
Example 4: Deferred Pension — Meera, Waiting Until 60
Profile: Meera has 28 years of service. Basic + DA is ₹14,500. She is healthy, still employed at 58, and wants to maximise her pension.
Inputs:
- Average Salary: ₹14,500
- Service: 28 years, 0 months
- Pension Start Age: 60
Calculation:
- Pensionable Salary: ₹14,500
- Rounding: 0 months, stays at 28 years
- 20-Year Bonus: Applicable (+2 years)
- Effective Service: 30 years
- Base Pension: (14,500 × 30) ÷ 70 = ₹6,214/month
- Deferred Enhancement: (60 − 58) × 4% = +8%
- Enhancement Amount: ₹497
- Final Pension: ₹6,711/month
Versus starting at 58 (₹6,214/month), she gains ₹497/month permanently by waiting 2 years. She foregoes ₹6,214 × 24 months = ₹1.49 lakh during the deferment. The breakeven point is ₹1,49,136 ÷ ₹497 = 300 months = 25 years — so she breaks even at age 85. Deferring pension makes financial sense only if you expect to live well past the mid-80s.
Example 5: Minimum Pension Floor — Ajay, Short Service
Profile: Ajay worked for 12 years before switching to self-employment. His Basic + DA was ₹9,000. He plans to claim pension at 58.
Calculation:
- Pensionable Salary: ₹9,000
- Rounding: 0 extra months → 12 years
- 20-Year Bonus: Not applicable (12 < 20)
- Effective Service: 12 years
- Base Pension: (9,000 × 12) ÷ 70 = ₹1,543/month
- Final Pension: ₹1,543/month (above the ₹1,000 floor)
Ajay’s pension is modest but real. Had his service been only 10 years and his salary lower, the floor would have kicked in at ₹1,000. The calculator flags this with a “FLOOR APPLIED” tag so you always know exactly which rule is determining your pension.
EPS Pension After 20 Years of Service
Twenty years of eligible pensionable service is an important milestone under EPS-95.
Where the applicable conditions are satisfied, two additional years are added as weightage for pension calculation. (EPF India)
For example:
20 years actual pensionable service
can become:
22 years for the pension calculation
using the standard formula:
₹15,000 × 22 ÷ 70 = ₹4,714 per month
The two-year weightage is an EPS pension calculation provision; it does not mean that two additional years of employment contributions were actually made.
EPS Pension at Age 58
For a member with the required eligible service, 58 is the normal superannuation pension age under EPS-95. The scheme also provides for early pension and deferred pension subject to the applicable conditions. (EPF India)
If you are approaching retirement, use the calculator above to compare your estimated pension under different commencement ages.
Can I Take EPS Pension Before 58?
Yes, eligible members can opt for early pension from age 50, subject to the applicable EPS conditions.
Early pension is reduced for each year by which the pension commencement date precedes age 58.
For example, starting pension earlier than 58 can substantially reduce the monthly pension you receive.
Use the calculator to compare the estimated pension at different commencement ages before making a retirement decision.
Can I Defer EPS Pension After 58?
Eligible members can defer pension beyond age 58, subject to the applicable EPS provisions.
Deferred pension can increase the pension amount for the eligible period of deferment, subject to the scheme rules.
The calculator can be used to compare different pension commencement ages and understand the effect on estimated monthly pension.
What Happens If I Have Less Than 10 Years of EPS Service?
Generally, 10 years of eligible pensionable service is required for a monthly EPS pension.
If you leave covered employment before completing the required service, you may be eligible for an EPS withdrawal benefit or may preserve your service through a Scheme Certificate, depending on your circumstances. (EPF India)
If you are close to completing 10 years of service, understand the consequences before choosing to withdraw your EPS benefit.
EPS Withdrawal Benefit vs Monthly Pension
If you have less than the required service for monthly pension, EPS provides a withdrawal-benefit mechanism under the applicable provisions.
You should distinguish between:
Monthly pension
A recurring pension payable after meeting the eligibility requirements.
Withdrawal benefit
A lump-sum benefit available in circumstances where the member is not eligible for monthly pension and the applicable withdrawal conditions are satisfied.
Scheme Certificate
A mechanism for preserving eligible pensionable service for future employment and pension benefits.
Your decision should take into account whether you may return to EPF-covered employment in the future.
What Is Higher Pension Under EPS?
Higher Pension refers to pension calculated on higher wages for members who meet the eligibility requirements under the applicable EPS provisions and the relevant higher-pension process.
It should not be confused with the standard EPS calculation using the ₹15,000 pensionable-salary ceiling.
The EPFO Pension Manual contains specific provisions and examples for pension on higher wages, including separate treatment of pensionable service before and after 1 September 2014. (EPF India)
If you are a Higher Pension member, use your applicable pensionable salary and service details rather than assuming the standard ₹15,000 calculation applies.
EPF vs EPS: What Is the Difference?
| Aspect | EPF (Employees’ Provident Fund) | EPS (Employees’ Pension Scheme) |
|---|---|---|
| Purpose | Provident fund savings | Pension scheme |
| Benefit Type | Builds an accumulated balance | Provides pension benefits subject to eligibility |
| Earnings | Interest is credited to the EPF balance | Pension is determined under EPS provisions |
| Employee Contribution | Employee contributes to EPF | Employee does not make a separate direct EPS contribution |
| Benefit Calculation | Amount depends on accumulated balance and interest | Pension depends on pensionable salary and service |
| Nature of Benefit | Lump-sum savings available as per rules | Monthly pension after meeting eligibility conditions |
| Relationship | Represents accumulated provident fund savings | Provides pension benefits under the Employees’ Pension Scheme |
How Much EPS Pension Will I Get?
Your pension depends mainly on:
1. Pensionable salary
The salary considered under the applicable EPS provisions.
2. Pensionable service
Your eligible EPS service.
3. Service weightage
The applicable two-year weightage for qualifying long service.
4. Pension commencement age
Starting before or after the normal pension age can affect the pension amount.
5. Higher Pension eligibility
Eligible higher-pension members may be subject to different pensionable-salary treatment.
Use the calculator at the top of this page to estimate your pension based on your circumstances.
How EPS Fits Into Your Overall Retirement Plan
EPS pension is one piece of a larger retirement income puzzle. Understanding where it fits helps you make smarter decisions about the rest of your planning.
EPF + EPS as a combined base. Your EPS pension provides a guaranteed monthly income. Your EPF corpus, accumulated separately, can be drawn down as a lump sum or through a Systematic Withdrawal Plan (SWP). Together, these cover the “guaranteed floor” of your retirement income. For a sophisticated look at how to structure the drawdown of a larger corpus, see the Retirement Withdrawal & SWP Calculator.
NPS as the variable annuity complement. NPS also mandates a 40% annuity purchase at withdrawal, giving you a second guaranteed income stream. Our NPS vs Mutual Funds comparison covers when NPS makes more sense than pure equity SIPs.
The SIP corpus fills the gap. For most salaried Indians, the EPS + EPF combination replaces only 30–50% of pre-retirement income. The gap must be filled by the equity + debt SIP corpus built over a career. Our Best SIP Strategy for Retirement 2026 and the Waterfall SIP Allocation guide explain how to structure this.
Healthcare is your biggest wildcard. EPS pension is not indexed to inflation, so its real value erodes every year. This makes healthcare planning especially important — a single hospitalisation can wipe out months of pension income. See our Healthcare Inflation Calculator to understand how medical costs scale as you age.
Sequence-of-returns risk is real even with guaranteed income. Having a pension floor reduces but does not eliminate this risk. If markets crash in your early retirement years while you also have a SIP corpus to draw from, the pension acts as a buffer. For a full treatment, see Sequence of Returns Risk for Indian Retirees.
If you are also considering early retirement, your EPS pension may not start at the same time as your income stops. Our FIRE at 40, FIRE at 45, and FIRE at 50 guides cover how to bridge the gap between FIRE date and pension start.
Frequently Asked Questions About EPS Pension
What is the maximum monthly pension under EPS?
With the revised pensionable salary cap of ₹25,000, the maximum EPS pension for standard members increases to ₹12,500 per month, or approximately ₹13,214 per month where the 2-year service bonus is applicable. Higher Pension members remain outside this cap and receive pension based on their actual pensionable salary.
What is the minimum pension under EPS?
The minimum monthly pension is ₹1,000, as set in 2014. However, this applies only if you have completed 10 or more years of qualifying service. Below 10 years, you are not eligible for monthly pension — only a lump-sum withdrawal.
Is EPS pension taxable?
Yes. EPS pension is taxable under the head “Income from Salary” or “Income from Other Sources” depending on whether you are still employed when you receive it. It is added to your total income and taxed at your applicable slab rate. However, most pensioners’ total income (EPS + other) may fall below the ₹3 lakh basic exemption limit (New Tax Regime) or ₹2.5 lakh (Old Regime). See our PPF vs ELSS vs NPS comparison for tax-efficient alternatives to consider alongside EPS.
Can I receive EPS pension while still working?
Yes, if you retire at 58 (superannuation). The rules allow you to start receiving EPS pension upon turning 58 even if you continue in employment, because EPS membership automatically ends at 58. However, for early pension (50–57), you must not be in employment when you claim.
What happens to EPS if I resign before 10 years?
If you have less than 10 years of qualifying service, you are not entitled to a monthly pension. You can either:
(a) Withdraw the EPS accumulation as a lump sum using Form 10-C, or
(b) Obtain an EPS Scheme Certificate and preserve your service history for future use if you rejoin covered employment.
Taking the lump sum makes sense only if you are permanently leaving the organised sector. If there is any possibility of returning to an EPF-covered job, the Scheme Certificate preserves your service credit.
How is EPS different from EPF?
EPF (Employees’ Provident Fund) is a savings account — money goes in, earns interest, and comes back to you as a lump sum on retirement or withdrawal. EPS is a defined-benefit pension scheme — contributions go into a pool managed by EPFO, and you receive a monthly pension for life regardless of how much was contributed on your behalf. You cannot “withdraw” EPS as a lump sum once you are eligible for monthly pension, except in specific early-exit scenarios.
What is the EPS Scheme Certificate and when should I get one?
A Scheme Certificate is a document EPFO issues when you exit employment before 10 years without withdrawing EPS. It records your service and salary for future use. If you later join another EPF-covered employer, your previous service adds to the new service, helping you cross the 10-year threshold. Always get a Scheme Certificate when leaving a job — never let early-career EPS accumulations go unclaimed.
What does “Higher Pension” mean and am I eligible?
Following the Supreme Court judgment of November 4, 2022, employees who were EPFO members before September 1, 2014, and whose employers had been contributing EPS on the actual salary (not capped), could jointly apply with their employer for Higher Pension. The window to apply closed in May 2023. If you applied and it was approved, your EPS pension is calculated on your actual average salary, not capped at ₹15,000. Check with your employer’s HR or your EPFO passbook to confirm your status.
Is the 2-year bonus service always added if I have 20+ years?
Yes — this is an automatic rule in EPS-95, not an optional benefit. If your rounded pensionable service reaches 20 years or more, EPFO adds 2 years to the service count for pension calculation purposes. You do not need to apply for this.
Can I nominate someone other than my spouse to receive EPS family pension?
EPS family pension rules are strict. The widow (or widower) is the primary beneficiary. If there is no surviving spouse, children under 25 receive children’s pension (25% of widow pension per child, max 2 children). If the widow remarries, children become “orphans” and receive orphan pension (75% of widow pension each). The scheme does not allow nomination to parents, siblings, or other relatives for the monthly family pension.
What if I worked for multiple employers? Does service add up?
Yes. EPS contributory service across all employers is cumulative, provided you transferred your PF account (via UAN) rather than withdrawing. When you join a new employer and link your UAN, all prior service is preserved. This is why UAN portability is critical — withdrawing your EPF/EPS at every job change destroys your pension entitlement.
Will my EPS pension increase after I start receiving it?
The base pension amount is fixed at retirement. EPFO does occasionally declare “pension relief” (a percentage increase for existing pensioners), but these are irregular and not guaranteed. EPS pension is not formally indexed to inflation, which is an important planning consideration — the real purchasing power of ₹5,000/month today will be significantly lower in 20 years. This reinforces the need for an inflation-adjusted corpus alongside EPS. Our article on how inflation erodes SIP corpus explains the mechanics in detail.
What is the difference between early pension and premature withdrawal?
Early pension (age 50–57) means you start receiving your monthly pension before the normal age of 58, at a permanently reduced rate. Premature withdrawal means you exit EPS entirely and take a lump-sum payout, forfeiting any future monthly pension. Once you are past 58 with 10+ years of service, you cannot take a lump-sum withdrawal — you must take the monthly pension.
How do I claim my EPS pension?
You claim EPS pension using Form 10-D filed with your regional EPFO office (or online via the member portal). You will need your UAN, Aadhaar, bank account details, and a joint declaration from your last employer. The processing time is typically 30–90 days. Pension is credited monthly to your bank account.
Is EPS pension available to self-employed or freelancers?
No. EPS covers only employees of establishments registered under the EPF & MP Act, 1952 (typically companies with 20+ employees). If you are self-employed, a freelancer, or work for an unregistered small employer, you are not covered under EPS. NPS (through the NPS Lite or All Citizens model) is the government-backed pension alternative for such individuals. See our NPS vs Mutual Funds guide for how to think about this.
Does EPS pension stop at the member’s death?
The member’s pension stops at death. However, the family pension (widow pension, children pension, or orphan pension) continues immediately to the eligible family member. Widow pension is paid until the spouse’s death or remarriage. Children’s pension is paid until each child turns 25. For planning purposes, the EPS Family Pension tab in this calculator gives you approximate figures for these dependent benefits.
What if my employer did not deposit EPS contributions?
This is unfortunately a real issue for employees of smaller or financially stressed companies. If your passbook shows contributions but your pension claim is rejected due to employer default, you can file a complaint with the regional EPFO office. EPFO has the power to recover dues from employers and credit the EPS account. Always monitor your EPFO passbook via the member portal for regular contribution credit.
Can NRIs receive EPS pension?
Yes. There is no residency restriction on EPS pension. If you qualified under EPS and later became an NRI, you can still claim your pension at the appropriate age and have it credited to an NRI bank account in India (NRO account). Consult with your bank on repatriation rules and applicable TDS.
How does EPS interact with my overall FIRE plan?
If you are pursuing Financial Independence / Retire Early, EPS is a guaranteed income floor that actually reduces the corpus you need. A ₹5,000/month EPS pension starting at 58 reduces the SWP requirement from your invested corpus by ₹5,000 × 12 = ₹60,000/year — which at a 3.5% safe withdrawal rate means you need ₹17.1 lakh less in your investable corpus. Use the Wealthpedia FIRE Number Calculator alongside this EPS calculator to get your net FIRE corpus target.
The calculator says my pension is very low. What can I do?
If your projected EPS pension is low (under ₹2,000/month), it is typically because of one of three reasons: (a) short service tenure below 20 years (missing the 2-year bonus and having fewer effective years), (b) salary capped at ₹25,000 when your actual contribution base was low, or early pension with a steep reduction. The honest answer is that EPS has structural limits — it was designed as a floor, not a replacement income. Building a robust SIP corpus is the primary lever. See our SIP calculator with inflation and the Step-Up SIP guide to accelerate your corpus building.
Can I claim both EPF and EPS withdrawal at the same time?
Yes. EPF withdrawal (Form 19) and EPS Withdrawal Benefit (Form 10-C) are filed together as a composite claim on the EPFO portal. You do not need to file two separate claims. When you select “Final Settlement” under Online Claim, the system processes both EPF and EPS simultaneously. However, if you want only a Scheme Certificate (EPS preserved) but want the EPF amount, you select EPF withdrawal separately and EPS Scheme Certificate separately — in which case two distinct selections are made.
What if I have less than 1 year of EPS service?
Table-D starts from 1 completed year. If you have less than 12 months of EPS contributions, you are not entitled to either monthly pension or the Table-D withdrawal benefit. However, the actual employer EPS contributions made may be refunded — the mechanism for this varies and is handled by EPFO directly based on your records. Raise a grievance with your regional EPFO office if you believe contributions were made on your behalf for a period below 1 year.
Does the EPS Withdrawal Benefit earn interest?
No. EPS is a defined-benefit scheme — your contributions go into a common pool managed by EPFO and there is no individual account earning interest. The withdrawal benefit is determined solely by Table-D, regardless of actual contributions or the interest EPFO earns on the pool. This is fundamentally different from EPF, where your individual account earns the declared rate (currently 8.25% for 2023-24) and the balance grows year on year.
I withdrew EPS at a previous job. Can I still claim pension on my current service?
Yes — but only for the current and subsequent service periods. The withdrawn service is gone and cannot be reclaimed. Your pension calculation will use only the service from your new start date. This is why withdrawing EPS between jobs is almost always a financial mistake for those planning long careers in the organised sector — ₹30,000–₹60,000 received today could cost you ₹1,000–₹3,000/month in pension for 20+ years.
Is there a deadline to claim EPS Withdrawal Benefit after leaving a job?
There is no statutory deadline to claim EPS Withdrawal Benefit, but practical constraints apply: dormant accounts can be difficult to process if your UAN is inactive, your employer’s PF trust has closed, or contact details have changed. EPFO also occasionally transfers unclaimed balances to a senior citizens’ welfare fund after extended inactivity. Best practice is to file within 3–6 months of leaving employment, or get a Scheme Certificate if you are unsure about future employment plans.
Will the EPS Withdrawal Benefit affect my EPF withdrawal eligibility?
No. EPS and EPF are separate accounts and claiming one does not affect the other. You can withdraw EPF (Form 19) and leave EPS as a Scheme Certificate, or withdraw both simultaneously, or withdraw EPS and leave EPF invested (if you are below 58 and not fully retiring). The flexibility exists — but the composite online claim is the simplest route for a complete final settlement.
What is the EPS pension formula?
The standard EPS formula is:
Monthly Pension = Pensionable Salary × Pensionable Service ÷ 70
The formula is specified under EPS-95. (EPF India)
What is the EPS pensionable salary limit?
Under the standard EPS-95 provision, pensionable salary is capped at ₹15,000 per month. Separate provisions can apply to eligible higher-pension members. (EPF India)
Is the EPFO wage ceiling now ₹25,000?
Yes. The Government increased the statutory wage ceiling for mandatory EPFO coverage from ₹15,000 to ₹25,000 effective 17 September 2026. (Press Information Bureau)
Does the ₹25,000 EPFO ceiling mean my EPS pension will be calculated on ₹25,000?
Not automatically. The EPFO mandatory-coverage wage ceiling and the EPS pensionable-salary ceiling are separate concepts. The standard EPS-95 provision continues to specify ₹15,000 as the maximum pensionable salary, subject to applicable higher-pension provisions. (EPF India)
What happens after 20 years of EPS service?
Where the applicable conditions are satisfied, two additional years of weightage are added to pensionable service for calculation purposes. (EPF India)
Can I take EPS pension at 50?
The normal superannuation pension age under EPS-95 is 58, subject to the scheme’s eligibility requirements. (EPF India)
Does an employee contribute directly to EPS?
There is no separate direct employee contribution to EPS. Under the EPS structure, the employer’s contribution is allocated between EPF and EPS as prescribed by the scheme.
Key Planning Takeaways
Knowing your EPS pension number is not just an academic exercise — it changes real decisions.
It sets your retirement income floor. Every guaranteed rupee per month from EPS is one less rupee you need your invested corpus to generate. A ₹6,000/month EPS pension at 4% withdrawal rate is equivalent to having ₹18 lakh extra in corpus. Factor it in before you panic about whether you have enough to retire.
It informs your early retirement math. If you want to FIRE at 45 but EPS doesn’t start until 58, you have a 13-year gap where EPS contributes nothing. The Wealthpedia Multi-Goal FIRE Planner lets you model this gap explicitly — building a bridge corpus for ages 45–58 and a perpetual corpus for post-58 life.
It guides when to retire. The Age Scenarios tab shows clearly whether deferring to 59 or 60 meaningfully improves your income. For most people, the 4% annual increase for deferral has a long breakeven (age 83–85). Unless you have strong health reasons to expect longevity, retiring at 58 rather than deferring is often the right call.
It reduces your annuity purchase need. Many retirement planners recommend buying an annuity at retirement for guaranteed income. If your EPS pension is already ₹5,000–₹7,000/month, your annuity need from NPS or other sources is correspondingly lower — and the corpus you need to accumulate through SIPs is smaller.
It is not enough on its own. This bears repeating. The maximum EPS pension is ₹7,929/month. India’s urban consumer inflation is 5–6%. For anyone with a monthly expense of ₹50,000 today, EPS covers at most 15% of retirement income needs. The remaining 85% must come from EPF, NPS, mutual funds, real estate rental income, or other sources. Understanding your savings rate and how it translates to retirement corpus is the next step.
Important Note About This Calculator
This calculator is intended to provide an estimate for financial planning and educational purposes.
EPS pension calculations can become more complex where a member has:
- Service before and after 1 September 2014
- Higher Pension eligibility
- Multiple periods of employment
- Non-contributory periods
- Early pension
- Deferred pension
- Service spanning different EPS provisions
Your final pension is determined by EPFO based on its records and the provisions applicable to your membership.
The Wealthpedia EPS Pension Calculator was built using official EPFO EPS-2026 rules and validated against published EPFO pension calculations. It implements the full formula — including the month rounding rule, the 20-year service bonus, early pension reduction (4%/year before 58), deferred pension enhancement (4%/year after 58, up to 60), the ₹1,000 minimum pension floor, and the Higher Pension toggle for members covered under the Supreme Court 2022 ruling. Few months ago, I had developed a basic EPFO Pension Calculator and based on the user feedbacks, I have design this comprehensive EPS Pension Calculator.
Unlike most tools, the calculator shows you every step of the calculation so you can verify the arithmetic independently. If you spot an error or have a specific edge case to report, use the contact page.
For the full suite of financial planning tools, visit the Wealthpedia Calculators hub.
Methodology & Data
The calculator and explanations on this page are based primarily on official EPFO and Government information.
- Employees’ Pension Scheme, 1995 — EPFO
- EPFO Pension Manual
- Ministry of Labour & Employment / Press Information Bureau — 2026 EPFO wage-ceiling notification and announcements
For the latest official information, refer to EPFO and Ministry of Labour & Employment.
Our tools and calculators are built using a robust combination of historical data, well-established financial models, and user-defined inputs to ensure relevance and practicality. Each tool incorporates carefully selected datasets—such as market returns, inflation trends, and regulatory frameworks—paired with proven methodologies like rolling return analysis, withdrawal rate modelling, and rule-based calculations.
To ensure reliability, every model undergoes rigorous design validation and back-testing against historical scenarios. We simulate real-world conditions across different market cycles to evaluate consistency and accuracy. Additionally, assumptions are regularly reviewed and refined to reflect changing financial environments.
We encourage users to explore the underlying methodology and assumptions behind each tool to better understand how results are generated, enabling more informed and confident financial decision-making.
This article was last updated in October 2026. EPS rules are set by EPFO and the Ministry of Labour. While every effort has been made to ensure accuracy, always verify your final pension amount with EPFO directly. The EPS Withdrawal Benefit calculator and Table-D values are based on EPFO EPS-2026 scheme rules as publicly available. Actual entitlements are determined by EPFO based on official contribution records. This content is for educational purposes only and does not constitute financial, legal, or tax advice. Consult a qualified advisor for personalised guidance. I am not a SEBI-registered financial advisor. See full disclaimer.